
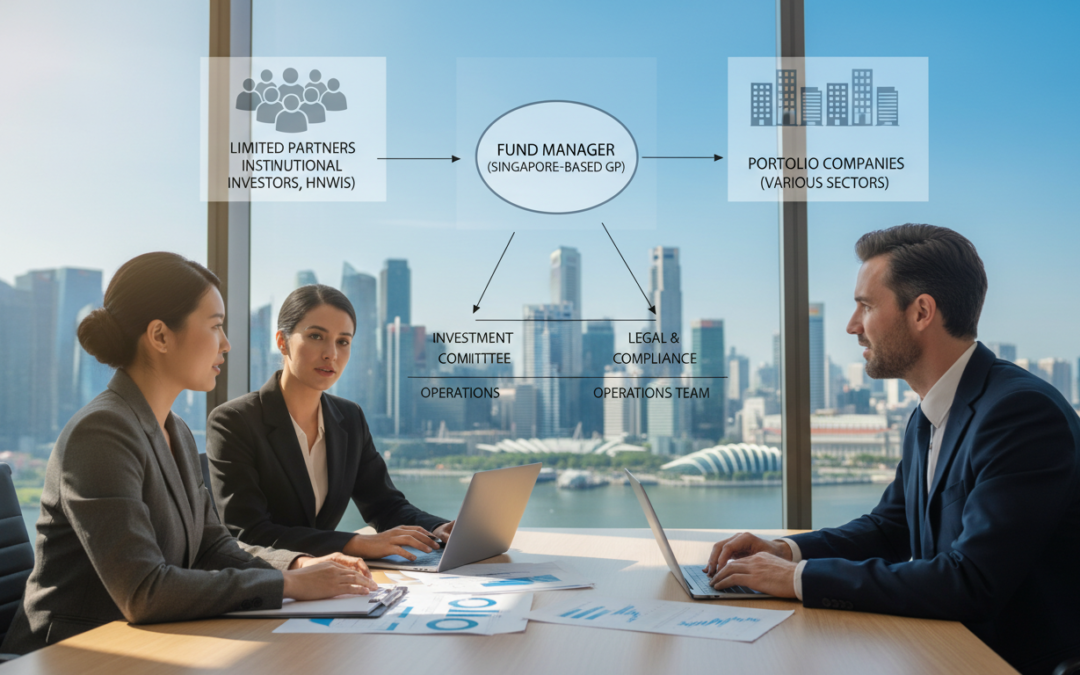
I still remember the first meeting with a nervous founder who needed clarity on fund set‑up. That moment taught me how legal choices shape trust, tax outcomes and the pace at which capital moves.
This guide explains what people mean by “private equity structure singapore funds” and sets clear expectations for practical, Singapore‑centric options. You will get a high‑level view of why a fund’s design matters for investor onboarding, distributions, governance and confidentiality.
We preview the three core vehicles used for regional strategies — limited partnerships, companies and the Variable Capital Company (VCC) — and note unit trusts where relevant. The audience includes fund managers, GPs, LPs, family offices and institutional investors searching for actionable comparisons.
The guide also signposts cross‑border models, the practical impact of the 2020 VCC regime, and the compliance “triggers” under the Securities and Futures Act. Expect plain terms from partnership documentation, lifecycle mechanics and how Singapore’s role as a services and business hub supports administration, custody and audit.
Key Takeaways
- Defines common vehicle options and what they mean in practice.
- Shows how choice affects onboarding, tax and governance.
- Summarises VCC, limited partnership and company uses.
- Highlights cross‑border considerations and master‑feeder models.
- Focuses on pragmatic documentation, lifecycle and compliance triggers.
Singapore’s private equity landscape and why fund structure matters today
Even as global assets under management slipped, Singapore’s market grew — MAS reported a 5.4% rise to US$2.5 trillion in 2018 while global AUM fell to US$74 trillion. That resilience underpins the city‑state’s appeal for managers and investors who run regional investment strategies.
Singapore as a Southeast Asian hub and services centre
Legal, tax, administration, custody, audit, banking and financing services are all available at scale. This ecosystem reduces execution risk and supports cross‑border investments from a single base.
How domicile, investors and strategy influence vehicle choice
Domicile is more than a formality. It affects treaty access, disclosure norms and regulatory obligations. Different investors expect different governance and documentation standards.
Strategy matters too. Closed‑ended models suit longer holding periods with capital calls. Evergreen or open models need redemption mechanics and liquidity planning.
What changed with the Variable Capital Company regime
The VCC Act (effective 14 January 2020) introduced a corporate vehicle tailored for fund use, with umbrella and sub‑fund options and flexible issuance and redemption at NAV. Managers now match vehicle choice to investor type, liquidity profile, tax position and where management activity happens.
How private equity funds work in practice
Understanding how a fund operates brings clarity to roles, cash flows and risk sharing. The typical lifecycle spans about 10 to 12 years, from fundraising through active investment, management and exit. This timeline shapes the legal and economic terms.
The GP–LP model and alignment of interests
The general partner manages day-to-day investment and decision-making. Limited partners commit capital and carry limited liability.
Alignment of interests is secured by carried interest — usually around 20% — only payable after returning capital and meeting any hurdle rate. This ties the manager’s upside to investor returns.
Key elements of the limited partnership agreement
The limited partnership agreement sets capital calls, investment period, recycling rules and the distribution waterfall. It also covers GP removal, key person events, advisory committee scope and expense allocation.
Lifecycle and fund economics
From first close, managers draw down committed capital, build a portfolio, drive value and then exit investments. Fees commonly include a ~2% management fee (often quarterly) and carry with clawback or preferred return protections.
| Phase | Primary activity | Governance focus | Common economics |
|---|---|---|---|
| Fundraising | Commitment and first close | Subscription terms, KYC | Commitment fees, management fee setup |
| Investment | Drawdowns and portfolio build | Investment restrictions, key person | Ongoing management fee |
| Realisation | Exits and distributions | Waterfall enforcement, reporting | Carry paid after hurdle |
| Wind-up | Final distributions | Clawback, audits | Final fee reconciliations |
Clear documentation reduces friction during fundraising. For assistance tailoring an agreement or choosing a model that supports your manager’s regulatory posture, contact us via our contact page.
private equity structure singapore funds: the main vehicles available
Below we set out the main legal forms managers typically select and how each aligns with governance, tax and distribution needs.
Limited partnerships under Cap. 163B
Limited partnerships are governed by the Limited Partnerships Act (Cap. 163B). The general partner has unlimited liability and handles active management. Limited partners keep liability to their agreed contribution so long as they do not “take part in management.” A statutory white list clarifies safe advisory activities for limited partners.
Why many managers choose partnerships
Partnership agreements give commercial flexibility on capital returns and profit splits. There are fewer company‑law constraints on distributions, so returns can be tailored by contract. For tax, partnerships are generally transparent — partners are taxed on their share of income rather than the entity being taxed first.
Companies, VCCs and unit trusts — key contrasts
Private limited companies face capital maintenance rules under the Companies Act, so dividends must come from distributable profits and redemptions have solvency tests. The VCC allows share issuance and redemption at NAV and may pay dividends from capital, with umbrella sub‑funds sharing administrators while segregating assets.
Unit trusts rely on a trustee holding assets under a deed; they suit investors seeking trust‑based governance and can also adopt umbrella designs for sub‑fund segregation.
Regulation, licensing, and offering rules for investment funds in Singapore
Regulatory assessment centres on whether investors pool assets and cede day-to-day control.
The SFA defines a collective investment scheme (CIS) by three core features: participants lack day‑to‑day control, property is managed as a whole by or on behalf of a manager, and contributions or profits are pooled so participants share income or gains.
Authorised versus recognised schemes and MAS obligations
Authorised schemes are Singapore‑constituted and generally need MAS authorisation, a registered prospectus and a product highlights sheet. Recognised schemes are overseas‑constituted but may need MAS recognition to be offered locally. In both cases the MAS Code on Collective Investment Schemes sets conduct, disclosure and custody expectations.
Common exemptions and practical traps
Managers often rely on exemptions for targeted offers. The usual routes are:
- offers to institutional investors only;
- restricted schemes for accredited investors (with MAS notification and annual filings);
- private placement to no more than 50 persons in 12 months; and
- small offers capped at SGD 5 million in 12 months.
Each exemption carries conditions. Advertising is typically prohibited and specific risk disclosures are required. Restricted schemes attract ongoing filing obligations that commonly surprise managers.
Manager licensing and the VCC regime
The choice of vehicle interacts with manager regulation. A VCC ordinarily must be run by a manager that is licensed or regulated by MAS, or one that fits an express exemption. This links corporate design to regulatory eligibility and practical operational terms.
Decision checklist: identify investor category, count and offer size, marketing approach, preferred vehicle and whether the intended manager status meets regulatory requirements. Early alignment avoids costly restructuring later.
Choosing the right Singapore fund structure for your strategy and investors
Choosing the right vehicle starts with matching investor liquidity needs to the mechanics of the legal form.
Closed‑ended strategies suit long holding periods and capital calls. Limited partnerships remain the common choice for long‑term returns. They restrict redemptions and simplify recycling and in‑kind distributions.
Open‑ended options and share redemption mechanics favour managers needing periodic liquidity. The VCC’s ability to issue and redeem at NAV helps where prompt redemptions matter. For a technical primer see understanding VCCs.
Tax positioning shapes treaty access and investor returns. Consider Section 13R, 13X and the Financial Sector Incentive when deciding domicile and capital flows.
“Align domicile with where management actually acts to avoid surprise tax and regulatory mismatches.”
| Consideration | Typical choice | Operational impact |
|---|---|---|
| Liquidity | LP (closed) or VCC (open) | Redemption timing, capital calls |
| Confidentiality | VCC / LP | Member registers limited; company registers public |
| Accounting | VCC flexible | SFRS, IFRS or US GAAP options |
For governance, use partnership agreements, constitutions or trust deeds to allocate decision rights. For practical terms and service conditions, review our terms and conditions.
Conclusion
What matters most is aligning investor expectations, capital mechanics and licensing early in the process.
The best fund choice depends on investor type, strategy and distribution needs. Limited partnerships give contractual flexibility and tax transparency. Companies offer familiar governance but stricter capital rules. The VCC adds NAV redemptions, umbrella efficiencies and tailored corporate features. Unit trusts suit trust‑centric oversight.
Get manager status and offering approach right from the start. Licensing or exemption limits can restrict marketing and onboarding if handled late.
Use this checklist: confirm target investors, define liquidity and distribution design, shortlist vehicle options, map tax incentives (13R/13X/FSI) and align documentation and governance. Also review liability boundaries and asset segregation for umbrella or cross‑border arrangements.
FAQ
What is a limited partnership and why is it commonly used for investment vehicles in Singapore?
How does the general partner differ from limited partners in responsibilities and liability?
What are the essential terms in a limited partnership agreement?
How do management fees, carried interest and hurdle rates typically work?
What is a Variable Capital Company (VCC) and what changed with its introduction?
When should managers consider using a private company rather than a limited partnership or VCC?
How do umbrella VCCs and sub-funds help with operational efficiency?
What regulatory triggers turn a vehicle into a collective investment scheme under the Securities and Futures Act?
What exemptions exist for offers to institutional and accredited investors?
Do VCCs require a licensed manager in Singapore?
How are returns and income taxed for limited partnerships and VCCs?
What governance documents should investors review before committing capital?
How can funds manage confidentiality and public disclosure of ownership?
What are common cross-border structuring approaches like master-feeder models?
Can a fund re-domicile into Singapore and what are the options?

Dean Cheong, CEO of VOffice, is a Singapore-based specialist in scaling B2B businesses. His work centers on optimizing sales operations, launching effective go-to-market strategies, and leveraging CRM tools to drive consistent revenue expansion. With a foundation in business banking and finance from Nanyang Technological University, Dean brings both strategic insight and real-world execution to every engagement.