
How long should founders truly expect to wait before their business can receive payments and pay staff?
This guide outlines realistic stages from ACRA incorporation to the first cleared transaction. Many overseas founders face stricter AML/KYC and Source of Wealth checks, so rapid approvals are the exception rather than the rule.
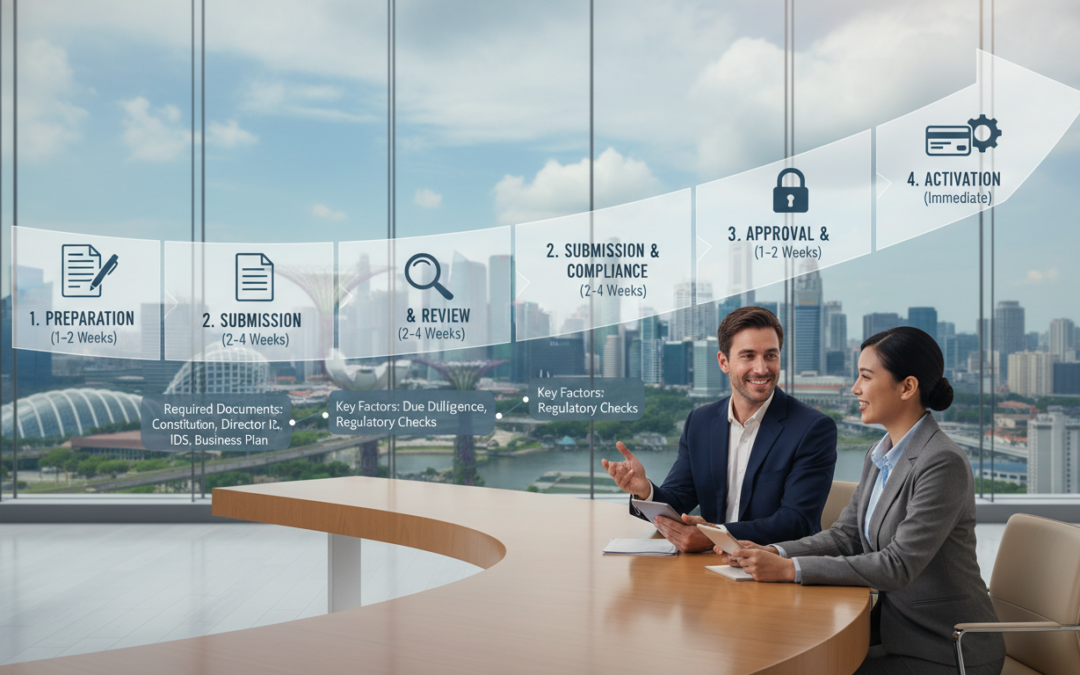
The sequence is clear: ACRA incorporation → UEN and company extracts → bank selection → application and interview → compliance review → activation. Knowing this order helps teams plan cash flow and vendor commitments.
Deciding point: choose a digital provider for speed or a traditional corporate bank for wider services and credibility. Delays can halt client receipts, payroll and supplier payments, so early planning matters.
Key Takeaways
- Expect enhanced compliance checks and longer processing with traditional providers.
- Typical windows range from a few days with some digital options to 4–8 weeks at conventional corporate banks.
- ACRA registration and a valid UEN are prerequisites before any assessment.
- Prepare clear Source of Wealth documents to reduce review delays.
- Plan operations (payments, payroll) around realistic activation dates to avoid interruption.
Why the corporate bank account matters for foreign-owned Singapore companies
A dedicated corporate bank account acts as the operational backbone for most Singapore-registered businesses. It turns registration documents into the means to receive payments and to meet daily financial obligations.
Payments, payroll and supplier settlements
A proper business account lets you receive customer funds, issue refunds and pay staff through auditable channels.
This reduces disputes and keeps payroll processing smooth when contractors or vendors expect local settlement.
Tax and regulatory administration with IRAS
Clear transactional records make tax reporting straightforward. Accurate accounts help claim deductible expenses and support GST filing.
Traceable income also reduces queries from tax authorities and speeds routine compliance checks.
Legal separation between business and personal finances
Keeping company funds separate protects directors and improves governance. It supports fiduciary duties and enhances transparency for partners.
Access to trade finance and business credit as you scale
Established banking relationships unlock letters of credit, trade finance and credit lines. These services support growth and ongoing management of international trade.
Quick comparison of typical service benefits
| Feature | Why it matters | Who benefits |
|---|---|---|
| Local payment rails | Faster receipts and reconciliations | Merchants, payroll teams |
| Online banking | Improved cash management and approvals | Finance managers, directors |
| Trade finance | Enables large cross‑border orders | Exporters, importers |
| Regulatory reporting | Simplifies IRAS submissions and audits | Tax teams, compliance officers |
What drives longer timelines for foreign applicants in Singapore
Stricter due diligence and proof of wealth documentation are common hurdles for non-resident founders. These checks explain why processing can stretch beyond initial expectations.
Enhanced AML, KYC and Source of Wealth scrutiny
Compliance is the first priority. Institutions apply AML/CTF rules and request detailed Source of Wealth and Source of Funds paperwork. Typical evidence includes bank statements, sale agreements and traceable capital receipts.
Limited local data matching
Non-resident profiles often lack matching government data. Automated checks fail more often, so manual verification and extra clarification become necessary. That adds time and follow-ups.
Transaction-risk and governance review
Review teams assess expected counterparties, countries, volumes and transaction patterns. High-risk flows trigger deeper checks. Clarity about beneficial owners and the role of directors improves the case.
These enhanced reviews commonly extend processing by several weeks. Preparation and consistent submissions reduce questions and speed approval. For practical next steps, consult the provider’s terms and conditions.
Pre-application checklist before any bank will assess you
Before any provider assesses your submission, a short set of legal and identity milestones must be completed.
Core incorporation steps
- Incorporate with ACRA and obtain a valid UEN immediately after registration.
- Secure current ACRA extracts (Business Profile) and the company constitution.
Local presence and representation
Many traditional providers expect a legally appointed local representative or a resident director. This reduces friction in verification and governance checks.
CorpPass and MyInfo Business
Have CorpPass ready if interactions with government-linked services are needed. Where supported, MyInfo Business can speed verification and cut manual entry errors.
Align filings and forms: ensure incorporation details match the paperwork you submit. Inconsistent data causes delays.
Readiness gate: if any checklist item is missing, extend your timeline estimates. Providers typically pause reviews until these basics are satisfied.
Bank options and how they affect speed and approvals
Choosing the right provider shapes how quickly your business can transact and what checks you’ll face.
Traditional local banks (eg. DBS, OCBC, UOB) offer deep product breadth and credibility. They usually request interviews, original documents, detailed due diligence and may ask for an initial deposit or minimum balance. Expect end-to-end processing to take around 4–8 weeks when manual checks are needed.
Digital banks and fintech providers
Challenger platforms such as Wise Business, Airwallex and Aspire speed onboarding with remote workflows and automated checks. Approvals often arrive in days, but services can be narrower and transaction limits may apply.
International banks
Global groups suit multi-currency treasury and cross-border needs. They can be selective, demanding higher opening balances and stricter proof of control. These providers reward established structures and clear trading corridors.
- Practical tip: use a fast digital route to start operations, then add a full-service option for credit and trade finance.
- Match provider choice to industry risk, expected corridors and document quality to avoid wasted applications.
bank account opening timeline for foreign owned singapore company
Expect a range of outcomes; some providers onboard swiftly, while others require several weeks of checks.
End-to-end ranges to plan around
Traditional providers commonly take 4–8 weeks. Digital platforms often finish in a few days to 1–2 weeks, sometimes up to 1–3 weeks for manual checks.
Where delays most often occur
Major time drivers include appointment scheduling (often 1–4 weeks), internal compliance review and iterative clarification requests about funds and activity.
When to start before go-live
Rule of thumb: start applications 6–8 weeks before you must send or receive payments to avoid payroll or supplier disruption.
“Prepare concise funds-flow notes and respond quickly to queries; this often cuts days off the process.”
| Stage | Typical delay | Impact |
|---|---|---|
| Appointment scheduling | 1–4 weeks | Holds verification and interview slots |
| Compliance review | 1–3 weeks | Requests for documents and clarifications |
| Complex transactions | Additional weeks | Extra due diligence and restrictions |
Note: approval does not always grant full functionality immediately. Early monitoring or limits can affect initial transaction capacity. The next section maps these stages into a practical, stage-by-stage plan.
Timeline stage breakdown from incorporation to activation
A practical schedule converts legal formalities into actionable tasks that finance teams can follow. Below is a compact stage-by-stage guide you can turn into an internal plan. It shows typical durations and key actions at each point in the process.
Company incorporation timeframes
Incorporation normally completes within 1–3 days once the filing is correct and directors’ IDs are ready.
Important: most providers will not progress without a valid UEN and recent ACRA extracts.
Document preparation and validation windows
Gather core documents in 3–5 days. Many reviewers prefer records issued within the last 1–3 months to reduce back-and-forth.
Clear, dated documents cut the number of clarification requests and speed approval.
Appointment scheduling lead times
Traditional providers often require 1–4 weeks to secure interview slots. This stage commonly dominates overall timing.
Bank review and approval periods for simple vs complex cases
Simple cases often finish in 1–4 weeks after interviews and file checks. Complex profiles — multi-layer ownership, overseas funding or higher-risk sectors — can extend to 6–8 weeks.
Tip: explain ownership, funds flows and expected counterparties clearly to limit extra queries.
Account activation, initial deposit, and online banking setup
After approval, activation usually takes 1–3 days. Some providers request an initial deposit and completion of authorised signatory forms before turning on full functionality.
Early transactions are often monitored. Align first payments with the stated business purpose to avoid holds.
| Stage | Typical duration | Key action |
|---|---|---|
| Incorporation | 1–3 days | Obtain UEN and extracts |
| Documents | 3–5 days | Prepare validated, recent files |
| Scheduling & review | 1–8 weeks | Interviews, compliance checks, approvals |
“Prepare concise funds-flow notes and respond quickly to queries; this often cuts days off the process.”
Documents banks require and how to assemble a bank-ready pack
A single, organised submission helps reviewers verify purpose and provenance quickly. Prepare a clear pack so the reviewer sees a coherent story from incorporation to first trade.
Corporate evidence
Include an ACRA Business Profile, constitution, registers of directors and shareholders, and a board resolution authorising signatories. These core documents show legal standing and authorised control.
Individuals and identity
Supply passport copies, proof of residential address (dated within three months) and short CVs or LinkedIn links for key controllers. This documentation proves who runs the business and their background.
Ownership and commercial proof
Provide an ownership chart that traces to ultimate beneficial owners. Add website links, signed contracts, invoices and a concise description of business activities. These items reduce follow-ups.
Financial evidence
Explain the source of initial capital and attach supporting bank statements, investor agreements or loan documents. Clear funds-flow information is often decisive during review.
“Index files, use consistent names and deliver one indexed PDF so reviewers can verify quickly.”
- Tip: match addresses and business descriptions across all files.
- Keep a single indexed PDF and a short cover note summarising the application.
How to choose the right account based on your business activities and transactions
Start by documenting expected flows. Note monthly volumes, average ticket sizes, typical counterparties and payment corridors. This mapping shows which provider best fits your business activities.
Expected volumes, counterparties and countries
List the countries you will pay and receive from. High‑risk jurisdictions can raise scrutiny and limit services. Clear corridors and repeat counterparties reduce review time and support higher transaction limits.
Multi-currency needs and FX
If you invoice in several currencies, a multi‑currency option matters. Compare FX spreads, wire charges and conversion windows. Smaller providers may offer cheaper cross‑border transfers but impose monthly limits.
Fees, balance requirements and core features
Compare monthly fees, per‑transfer charges and inward or outward remittance costs. Watch penalties for dropping below a minimum balance. Choose providers whose pricing suits projected cashflow.
Operational features and ongoing management matter as much as price. Look for authorisation workflows, role-based access, statement exports and API integrations that simplify reconciliation.
“Score providers against your mapped flows and pick the option that scales with growth.”
Remote vs in-person onboarding in Singapore
Deciding whether to attend in person or use remote verification is one of the clearest determinants of how long onboarding will take.
When traditional providers typically request a physical visit
Most traditional bank teams still ask that at least one authorised director attends a face-to-face interview. This is common when original identity checks, mandate signing and a business discussion are required.
Such visits help reduce follow-up queries but add planning and possible travel delays.
Video KYC scenarios and what to prepare
Some providers accept video KYC. Be ready with clear ID, recent proof of address and a quiet space with a stable connection.
Tip: answer consistently and have digital copies uploaded before the call to speed verification.
Planning travel: realistic booking and visit duration
Book interviews 1–4 weeks ahead and budget 1–2 working days on-site in case of extra checks. Bring original documentation even if you submitted scans.
Note: all authorised signatories may be asked to appear, so finalise governance early to avoid rescheduling.
- Remote workflows can accelerate the opening process but may limit features initially.
- If travel is uncertain, prioritise providers with robust remote processes and clear documentation standards.
Step-by-step account opening process that banks follow
Knowing what happens after you submit an application turns waiting into practical preparation. The typical process follows clear stages that reviewers run through before activation.
Preparing a clear business explanation banks can verify
Provide a concise description of what you sell, who your customers are and why you operate here. Explain expected volumes and payment corridors. Match this narrative to invoices, contracts and incorporation records.
Submitting the application and keeping information consistent
Use identical names, addresses and roles across forms and supporting files. Inconsistent information triggers queries and slows review.
Interview or meeting: likely compliance and business questions
Expect questions on customers, suppliers, transaction sizes, source of funds and operational plans. Answer clearly and stick to the written submission.
Internal due diligence and risk scoring
Review teams perform background checks, AML/KYC screening and industry risk scoring. This stage often takes the longest while reviewers validate commercial substance.
Responding to follow-ups without extending the process
- Designate one point of contact.
- Send an indexed document pack and short written answers.
- Reply promptly and consistently to avoid extra cycles.
“Disciplined execution is the leading predictor of approval and long‑term success.”
What banks evaluate when deciding approval
When deciding whether to grant approval, reviewers treat the request as a risk assessment rather than a paperwork checklist.
Operational presence and commercial substance
Commercial substance means a credible operating address, verifiable customers and proof of trading or contracts. Evidence of staff or contractors and a realistic execution plan adds weight.
Industry risk and regulated activities
Regulated sectors attract deeper scrutiny. Payments, remittance and virtual asset services often require licences and raise extra questions about controls and compliance.
Director residence and governance credibility
Reviewers assess whether directors can be contacted and whether decision making is clear. Experienced, resident directors make approval more likely.
Source of funds and expected usage patterns
Banks expect documentary proof of initial capital and a plausible funds‑flow narrative. Projected volume, frequency, counterparties and jurisdictions must match the business description.
“Design your submission to answer these points upfront to reduce follow-up requests.”
| Evaluation area | What reviewers check | Impact on approval |
|---|---|---|
| Substance | Address, contracts, staff | Speeds decision |
| Industry risk | Regulatory licences, sector controls | May trigger deeper review |
| Governance | Directors, mandates, signatories | Builds trust |
| Funds & usage | Source docs, expected flows | Aligns risk to activity |
Common reasons applications are rejected or delayed
Review teams flag many submissions because the operational story lacks concrete evidence. That single gap often turns a straightforward submission into weeks of follow-up.
- Vague business description: Generic summaries such as “consulting” without niche, customer types or deliverables force reviewers to ask repeated questions.
- Weak proof of occupancy: Virtual office addresses often raise red flags. Provide lease copies, utility bills or photos to show real presence.
- Unclear source of funds: Missing bank statements, absent investor agreements or poor funds-flow documentation are leading causes of delay.
- Inconsistent data across forms: Mismatches between incorporation filings, submitted documents and application fields damage credibility.
- Complex jurisdictions or flows: Layered payments, high-risk countries or unusual transactions require a clear commercial rationale and supporting evidence.
Most rejections are procedural and avoidable. Submit up-to-date documents, match names and addresses exactly, and include a short summary that ties your description to real contracts and receipts.
“Clear, consistent documentation reduces queries and speeds decisions.”
How to shorten approval time and improve your chances
Reduce friction in the review process by presenting a single, verifiable narrative. A clear pack and prompt replies cut review cycles and let you start trading sooner.
Write a concise one-page business and funds-flow summary
Prepare one page that states what you sell, who pays you and typical invoice sizes. Include projected monthly volumes and the origin of initial capital.
Demonstrate operational substance with documents banks trust
Attach dated evidence that compliance teams can verify quickly. Useful items include signed contracts, recent invoices, a working website link, lease or serviced office proof and a clear ownership chart.
Apply to multiple banks strategically
Submit to a mix of two to three providers: one digital and one traditional. This reduces single‑point risk and often shortens total time to operation.
Consider appointing a Singapore-resident director
When suitable, a resident director improves local governance credibility. That step can speed interviews and raise the odds of swift approval.
Response discipline is key: nominate one contact, deliver an indexed pack and answer queries within 24–48 hours.
“Clear evidence and fast replies reduce follow-ups, shorten internal review and increase probability of success.”
Costs and operational constraints to plan for after opening
Costs and operational limits after activation often surprise new founders unless they plan ahead. “Account opened” is not the end: minimum balances, monitoring and ongoing fees all affect cashflow.
Initial deposits and minimum balance mechanics
Traditional providers often ask for an initial deposit in the S$1,000–3,000 range. This initial deposit varies by product and may be higher for corporate-grade services.
Maintain a clear buffer above the stated minimum. Falling short can trigger monthly penalties that compound early-stage burn.
Monitoring windows and transaction limits
New relationships typically undergo 3–6 months of monitoring. During this period, some high-value or cross-border payments may be capped.
Banks lift limits as usage matches the stated business purpose and volumes. Provide clear invoices and flow notes to expedite normalisation.
Fees that matter to SMEs
Watch monthly maintenance charges, local FAST/PayNow costs, international transfer fees and FX margins. Card and cheque fees can also reduce liquidity.
Tip: compare fee tables across providers and model monthly spend against runway.
| Item | Typical range | Impact |
|---|---|---|
| Initial deposit | S$1,000–3,000 | Immediate funding requirement |
| Minimum balance | S$0–S$5,000 | Penalty risk if breached |
| Monitoring period | 3–6 months | Transaction limits may apply |
| Monthly fees & transfers | S$0–S$100+ | Ongoing operational cost |
“Plan balances and fees into your cashflow model to avoid surprises during the early months.”
- Set up alerts and reconcile weekly.
- Assign roles to control payments and review limits.
- Keep a buffer above minimum balance to avoid penalties.
Cost planning should influence provider selection. Choose a partner whose pricing and limits match expected volumes and operations.
After approval: staying compliant so the account remains operational
Ongoing oversight after approval keeps the relationship active and prevents sudden restrictions. Treat post‑approval compliance as part of regular operations rather than a one‑time hurdle.
Aligning real transactions with stated business activity
Use your facility in line with the declared business purpose. When actual transactions match the submitted funds‑flow narrative, teams see fewer alerts and fewer holds.
Keep invoice types, counterparties and payment sizes consistent with the original submission. If you change activity, notify the institution promptly.
Ongoing reviews, compliance questionnaires, and record‑keeping
Expect periodic KYC refreshes and short questionnaires. These may ask for updated corporate information, beneficial owner changes and recent transaction samples.
Maintain concise records: contracts, invoices, delivery evidence and bank statements. Indexed files let you respond within 24–48 hours and cut needless follow ups.
When checks link to tax and reporting
Financial institutions may coordinate checks tied to tax or regulatory reporting. Clean accounting and clear transaction rationale make these exchanges straightforward.
Update them on director, owner or signatory changes and any new addresses. Prompt governance updates maintain trust and reduce the chance of restrictions.
“Treat the relationship as a controlled operational process: timely, consistent information and clear records keep operations smooth.”
When professional support can save weeks
An experienced corporate services team removes routine friction and keeps applications moving. This support streamlines the onboarding process and often trims avoidable delays by several weeks.
Bank selection matched to your profile and industry
Advisers match providers to your risk profile, sector and transaction patterns. That improves the chance of a smooth review because they know which institutions favour specific industries and governance structures.
Bank-ready documentation preparation and application logistics
Specialists assemble consistent packs so reviewers see a coherent story. They make sure each document is current and formatted to the ways banks require.
They also handle the practical side of the application: booking interviews, coordinating signatories and ensuring authorised people are available for calls.
Coordinating interviews, follow-ups, and clarifications efficiently
After submission, advisers manage queries, draft concise replies and track outstanding items. Rapid, single-point communication reduces back-and-forth and shortens turnaround time.
- When to seek help: complex ownership, tight go‑live dates, higher‑risk sectors or limited travel prospects.
- What to expect: faster, cleaner submissions but no guarantees—final approvals remain with the provider.
“Good advisers improve speed and accuracy, making the whole experience far less administrative for entrepreneurs and small businesses.”
Conclusion
A focused, milestone‑driven approach turns a slow process into predictable progress.
Opening a corporate bank account is achievable, but success hinges on preparation, provider choice and a clear risk narrative. Start early: scheduling interviews and compliance reviews often set the critical dates.
Key success factors are simple. Provide a short business and funds‑flow note, show transparent ownership, and supply credible proof of funds. Match names and dates across every document to avoid delays.
Choose whether a fast digital route suits initial operations, then add a full‑service corporate bank as you scale. Remember ongoing monitoring, fees and minimum balances after activation.
Act now: incorporate, assemble a bank‑ready pack, shortlist providers, draft a one‑page summary and respond quickly to queries. For further practical steps, see our Singapore corporate bank account guide.
FAQ
What is the typical timeline to open a corporate bank account for a foreign-owned Singapore entity?
Why do institutions take longer with non-resident applicants?
What pre-application steps reduce delays?
Do I need a resident director or local representative?
What documents must I include in a bank-ready pack?
How much does an initial deposit speed up activation?
What are the most common reasons for rejection or delays?
How do different providers affect speed and suitability?
Which parts of the process usually cause the longest delays?
Can the whole process be done remotely?
How should I choose the right provider based on my business activity?
What should I expect during the interview or meeting?
How long after approval before I can transact?
What ongoing obligations should I plan for post-approval?
How can I reduce overall approval time?
When should I start the process if I have a go-live date?
Are fees and minimum balances significant for startups?
When is it worth hiring professional support?
What triggers increased ongoing monitoring after account opening?
How important is demonstrating commercial substance in Singapore?

Dean Cheong, CEO of VOffice, is a Singapore-based specialist in scaling B2B businesses. His work centers on optimizing sales operations, launching effective go-to-market strategies, and leveraging CRM tools to drive consistent revenue expansion. With a foundation in business banking and finance from Nanyang Technological University, Dean brings both strategic insight and real-world execution to every engagement.