
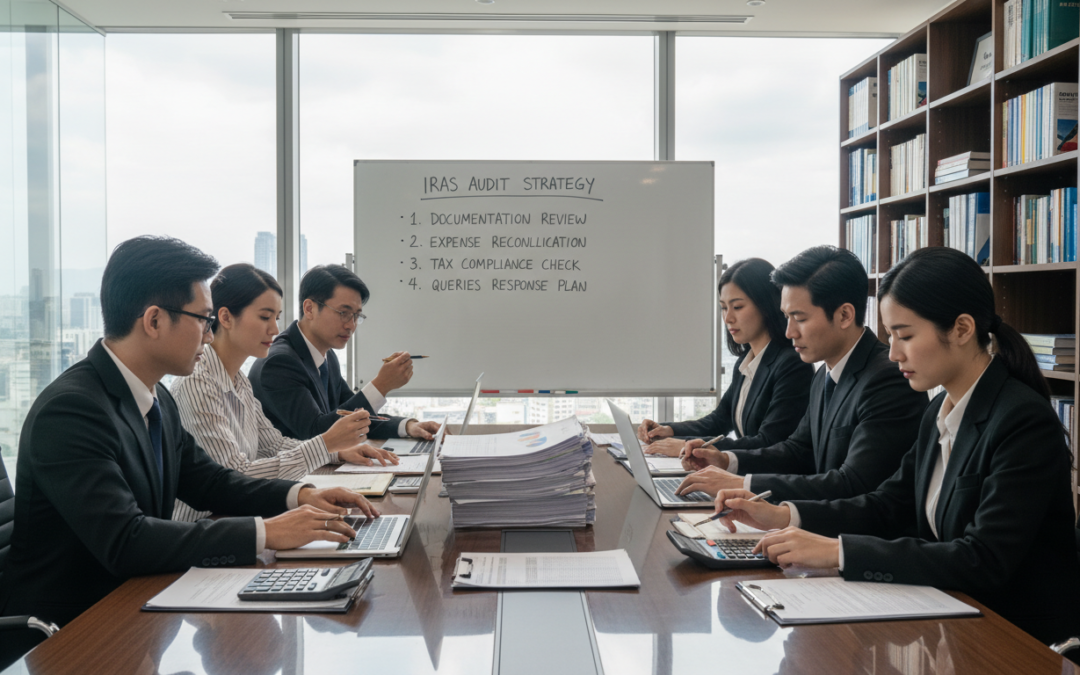
Ever wondered whether a routine review means you are under suspicion, or simply part of the Inland Revenue Authority’s checks?
This guide explains what an IRAS audit seeks to verify and sets calm expectations. An inspection confirms correct income reporting and tax paid, and it may arise from risk profiling, random selection, or third‑party matching.
We outline a practical, step‑by‑step approach focused on clear documentation, year‑round reconciliations and disciplined record retention. Small and medium enterprises, finance managers and founders will find advice on assembling invoices, bank statements, payroll and contracts.
The article previews desk versus field reviews, pre‑check routines, conduct during a visit and sensible post‑review actions. It also highlights common focus areas such as GST, corporate income and related‑party dealings.
Professional tax advisory services can help with document packs and communications, without promising outcomes. The goal is simple: be audit‑ready so responses are swift and well organised.
Key Takeaways
- An IRAS review is a verification, not an automatic allegation of wrongdoing.
- Keep neat records and reconciliations year‑round to reduce stress if selected.
- Assemble supporting documentation: invoices, statements, CPF and payroll files.
- Know the difference between desk checks and on‑site inspections.
- Seek professional services for complex queries and clear communication.
Understanding an IRAS audit in Singapore and why it happens
An IRAS review checks whether declared figures match underlying paperwork and business reality.
“Inspectors look beyond totals and expect clear trails from bank entries to invoices.”
What is reviewed:
- Declared income and income tax computations.
- Accounting books, financial statements and supporting records.
- Bank accounts, transaction listings and reconciliations.
Selection follows a mix of risk profiling, targeted industry campaigns and random checks. The inland revenue authority uses data analytics and third‑party matching (ACRA, CPF, suppliers) to flag anomalies.
Analytics may spotlight sudden margin drops, persistent GST refund positions or figures out of line with benchmarks. Small data‑entry errors can still prompt follow-up questions, so internal reconciliations matter even when amounts seem minor.
Common triggers include mismatches between GST and accounts, unusual year‑on‑year swings, frequent refunds or heavy cash receipts without proper documentation. Sectors such as F&B, retail and construction often attract closer scrutiny because of cash handling and variable income.
Next: the process can be a desk review or a field visit, and the level of disruption differs significantly.
Types of IRAS audits you may face: desk audit vs field audit
Audits range from quick document checks to in-depth on-site inspections that probe systems and stock. Knowing the distinction helps businesses anticipate disruption and allocate resources.
Desk audit: clarifications, document requests and myTax Portal submissions
Desk reviews usually begin with a letter or email asking for clarifications on specific line items. Responses are uploaded via myTax Portal along with supporting documents such as invoices, bank statements and reconciliations.
If records are orderly, a desk review can conclude within weeks. Speed depends on responsiveness, record quality and the volume of transactions under review.
Field audit: on-site visits, staff interviews, inventory checks and system reviews
Field work is more intensive. Officers may tour premises, interview staff, sample transactions and count inventory. They will also examine accounting systems and internal controls.
Complex field exercises can take months or, in severe cases, up to a year. The process demands sustained co‑ordination between finance teams and operations.
- Reduce friction: keep a clean document index, consistent ledgers and reconciled bank‑to‑book figures.
- Prepare staff: ensure key personnel can explain transaction flows clearly and consistently.
- Assign an owner: appoint an internal representative to manage queries and communications.
how to prepare for iras audit singapore with an audit-ready mindset
When a tax review arrives, quick organisation and clear ownership protect your company.
Stay calm and professional. A measured reply in the first 24–48 hours prevents contradictions and keeps channels open. Avoid speculative explanations; note queries and promise prompt, evidence-based responses.
Confirm scope, years and deadlines
Read the notice carefully. Identify the exact scope, the Years of Assessment covered and the documents requested.
Record submission deadlines and flag any dates where extensions may be needed.
Assign roles and consider representation
Appoint a single point of contact—typically the finance lead—to handle version control and timetables.
Decide early about engaging a tax agent or representative. They can liaise with IRAS, draft explanations, prepare schedules and manage submissions.
- Keep stakeholders aligned: directors, payroll, operations and finance.
- Maintain an audit log of files sent and questions answered.
- Before sending anything, run structured pre-audit checks to spot discrepancies.
Pre-audit checks: review tax returns, filings and high-risk areas
A focused pre-audit check can spot mismatches long before an enquiry arrives. Start with short, methodical reviews that flag the items most likely to trigger scrutiny.
Reconciling statements and tax computations
Tie your financial statements to income tax computations and GST returns. Trace variances from totals down to ledger entries and source documents. Where numbers differ, attach a quick note that explains the cause and links to evidence.
Large deductions, losses and unusual year-on-year movements
Check big deductions, capital allowance claims and recurring losses within a three‑year window. Prepare concise, fact‑based explanations for margin shifts, expense spikes or sudden drops in income.
Cash transactions and suspicious items
For cash-heavy receipts, document counterparties, business purpose and approval trails. Avoid mixing personal spending with company records. Keep receipts, deposit slips and client confirmations handy.
Timely and complete submissions
Late or incomplete filings raise compliance risk. Fix genuine errors promptly with professional advice and keep a log of corrections and reasons.
| Risk area | Common discrepancy | Immediate action | Evidence to gather |
|---|---|---|---|
| GST vs revenue | Sales not in returns | Reconcile bank deposits | Invoices, bank slips |
| Large deductions | Unsupported expenses | Validate business purpose | Contracts, receipts |
| Cash receipts | Undeclared income | Match deposits to sales | Payment records, logs |
Next step: strong reconciliations matter only if each number links to retrievable records. That leads into building a complete documentation pack.
Building your IRAS audit documentation pack
A compact, well-indexed documents bundle saves time when examiners ask for proof. Start by separating source papers from derived reports.
Key source documents
Gather: sales and purchase invoices, receipts, credit notes and signed contracts. Keep each invoice linked to the related ledger entry and reconciliation note.
Banking, payroll and ledgers
Include bank statements, deposit slips and a mapping sheet that ties bank lines to ledger postings. Add payroll summaries, CPF contribution records and calculations for bonuses or allowances.
Organise for fast retrieval
- Consistent file naming and indexed folders by year and tax type.
- Cross-reference ledger entries with document IDs for quick tracing.
- Create a read-only data room or controlled shared folder to reduce disruption during an inspection.
| Pack section | What to include | Purpose |
|---|---|---|
| Source documents | Invoices, receipts, credit notes, contracts | Evidence of income and spending |
| Financial records | Ledgers, reconciliations, statements | Link return figures to source |
| Payroll files | Payroll summaries, CPF records, bonus computations | Support employment tax positions |
Retention note: Keep legible digital copies with version control and sensible backups for at least five years. Limit access and track changes.
For internal policy references, review your terms and conditions.
What IRAS commonly reviews during a tax audit Singapore
Officials typically prioritise GST, corporate income positions, related-party dealings and employment reporting. This focus helps businesses allocate effort where exposure is highest.
GST compliance
Output tax — IRAS checks that sales carry the correct tax and that nothing material is omitted.
Validate totals with sales ledgers and POS reports.
Input tax — Claims are tested for blocked items and proper tax invoices. Keep supplier invoices, import permits and proof of payment.
GST audits overview is useful when assessing documentary evidence for zero-rated exports such as bills of lading and export permits.
Corporate income tax
Review points include revenue recognition timing, cut-off issues and unrecorded income.
Keep contracts, delivery notes and payment confirmations to support income figures.
Expenses must be wholly and exclusively for business use. Retain receipts, supplier agreements and approvals for large deductions.
Related-party transactions
IRAS expects arm’s length pricing. Document transfer pricing policies, comparable evidence and intercompany invoices.
Employment tax
Check AIS reporting for bonuses, allowances and benefits-in-kind. Maintain payroll runs, CPF records and employment contracts as proof of declared amounts.
Practical rule: substantiate each amount with matching records across systems rather than supplying excessive, irrelevant material.
During the audit: communication, transparency and protecting your position
When examiners request information, a calm, structured reply preserves credibility and speeds resolution.
Responding to requests and managing deadlines
Acknowledge requests immediately and confirm the exact scope in writing. IRAS often sets submission deadlines of 14–21 days; flag any constraints early.
If more time is needed, request an extension promptly with reasons and a clear delivery date. Assign owners and submit complete packs rather than piecemeal files to avoid confusion.
Explaining discrepancies with evidence
Do not guess or offer off‑the‑cuff numbers. Present a concise narrative for each discrepancy and attach reconciliations, invoices and bank lines that support the explanation.
Use a single representative for technical points so responses remain consistent. Professional tax services can draft precise explanations and reduce the risk of inadvertent misstatements.
Protecting sensitive data and limiting access
Provide only requested documentation and keep transfers on controlled channels. Restrict sensitive records to authorised staff and keep a response log for every submission.
| Action | Target timeline | Owner | Documents required |
|---|---|---|---|
| Acknowledge request | Within 24 hours | Primary contact | Request letter, query list |
| Submit evidence pack | 14–21 days (or agreed extension) | Finance lead | Invoices, reconciliations, bank statements |
| Request extension | As soon as limit identified | Appointed rep | Reason note, proposed delivery date |
| Maintain confidentiality | Ongoing | IT & compliance | Access logs, secure links |
For guidance on individual inspections, review audits on individuals by IRAS.
After the audit: outcomes, penalties and next steps
At the conclusion of a review, expect a findings notice that explains which returns will be amended and the resulting tax position. The letter will list adjustments, show computations and state any additional tax payable. Payment deadlines and procedural steps normally follow.
Understanding the findings letter and additional tax
Start by validating calculations against your records. Check amounts, years covered and the description of each adjustment.
Practical check: mark whether differences are factual (missing invoices) or interpretive (tax treatment).
Penalties and late filing exposure
Penalties for incorrect returns can be severe. Multipliers often range widely depending on behaviour; careless mistakes attract higher sanctions than genuine errors.
Late filing or late payment also carries fixed penalties (commonly from S$200) plus interest. Settling promptly reduces compounding costs.
Disputes, Notice of Objection and voluntary disclosure
If you disagree, compile evidence and draft a clear explanation. File a Notice of Objection within the statutory time and seek adviser support.
Voluntary Disclosure: benefits under the VDP apply only when disclosure occurs before the authority notifies a review of those items. Regular internal checks make that possible.
| Action | Risk | Penalty | Timeframe |
|---|---|---|---|
| Accept adjustments | Immediate payment | Additional tax | As stated |
| Object | Reassessment | Possible reduction | Within statutory period |
| Voluntary disclosure | Pre-notification only | Lower penalty | Before notice |
Lessons learned: update controls, tighten reconciliations and train staff so records and filings are cleaner next time. For privacy handling of documents, review our privacy policy.
Conclusion
,Treating compliance as a regular business routine makes external checks workable and predictable.
Keep a steady rhythm of digital trails, reconciliations and indexed records. These habits turn an official review into a manageable admin task rather than an operational shock.
Remember the sequence covered: know why reviews occur, identify the review type, adopt the right mindset, run pre‑checks, assemble a clear documentation pack and reply promptly with evidence.
High‑impact habits: monthly or quarterly reconciliations, legible five‑year records and disciplined handling of GST, income and payroll reporting.
Consider engaging professional services for an independent review, representation or process improvements if transactions are complex. A small investment now saves time and risk later.
FAQ
What does an Inland Revenue Authority of Singapore tax review typically examine?
Why might a business be selected for a tax inspection?
What is the difference between a desk review and an on-site field visit?
What should a company do after receiving an IRAS notification?
Which pre‑audit checks reduce exposure to adjustments?
What documents are essential for an audit pack?
How long must businesses retain records relevant to a tax inspection?
Which GST areas receive close attention during a review?
What corporate income tax matters are often probed?
How should businesses respond to IRAS information requests?
Can an assessment be challenged if adjustments are made?
What penalties might follow after an inspection?
When should a business consider engaging a tax professional?

Dean Cheong, CEO of VOffice, is a Singapore-based specialist in scaling B2B businesses. His work centers on optimizing sales operations, launching effective go-to-market strategies, and leveraging CRM tools to drive consistent revenue expansion. With a foundation in business banking and finance from Nanyang Technological University, Dean brings both strategic insight and real-world execution to every engagement.